business
2 Mild Storm Seasons Cushion Insurers Before Hurricane Isaias
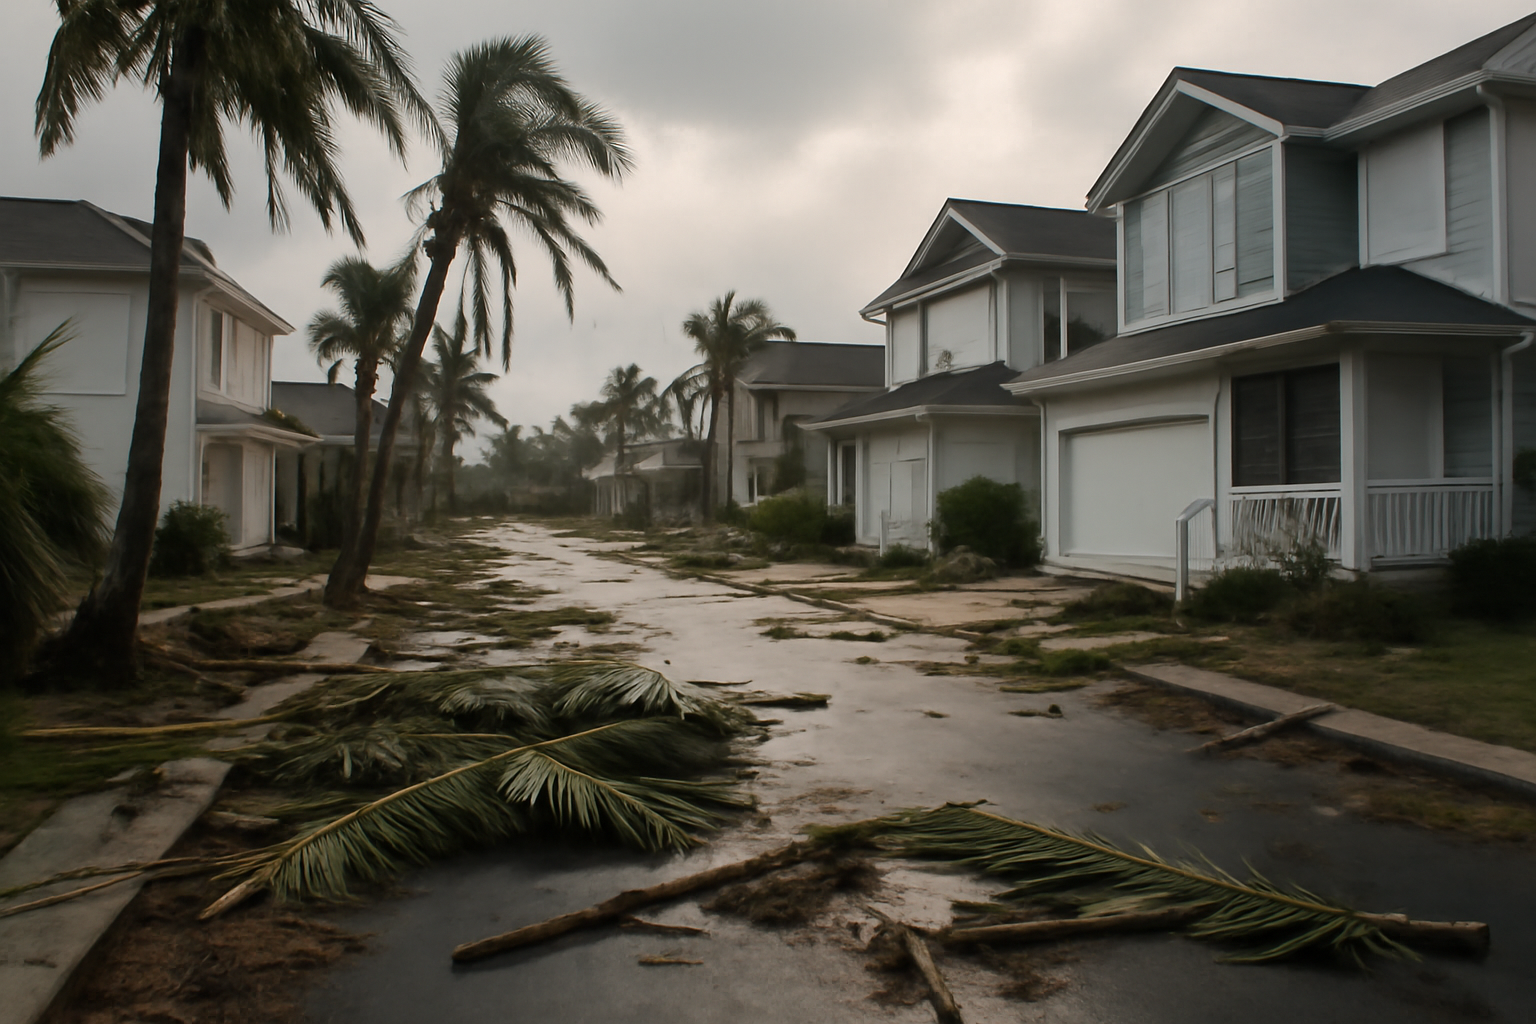
Hurricane Isaias could cost insurers single-digit billions of dollars, according to Matthew Palazola, senior insurance equity analyst at Bloomberg Intelligence, who spoke Oct. 10, 2026, with hosts David Gura and Christina Ruffini on Bloomberg This Weekend. For Florida homeowners and insurance company shareholders, the number matters because it sets the range for what claims adjusters, reinsurers and investors should expect in the weeks ahead.
What did Bloomberg's analyst say about Hurricane Isaias' cost to insurers?
Palazola told Bloomberg that insured losses from the storm are likely to land in the single-digit billions, not the double-digit figures that have followed some past Florida hurricanes. He pointed to two factors working in insurers' favor: tougher building codes that have been in place for newer Florida construction, and a buildup of capital reserves after two comparatively mild hurricane seasons. Those reserves give insurers more room to absorb a storm like Isaias without triggering the kind of market stress that followed earlier, costlier hurricanes.
Quick numbers
- Estimated insured losses: single-digit billions of dollars, per Palazola
- Mild hurricane seasons before Isaias: two, cited by Palazola as capital-rebuilding years
- Florida property values: described by Palazola as rising, which normally pushes loss totals higher
Why might stronger Florida building codes limit the damage?
Florida has required tougher wind-resistance standards for new construction for years, and Palazola said that upgrade is now showing up in the numbers. Homes and commercial buildings built to current codes tend to hold up better in wind events than older structures, which lowers the dollar amount insurers have to pay out per damaged property. That matters even as Florida property values climb, because higher values alone would normally push total insured losses higher. Palazola's point is that code-driven resilience is offsetting some of that value growth, at least in this storm.
How are two mild hurricane seasons helping insurers now?
According to Palazola, the two hurricane seasons leading up to Isaias were relatively mild, meaning insurers did not face the large claims payouts that can drain capital reserves. That gave carriers time to rebuild their balance sheets. Entering this storm with stronger capital positions means insurers are better positioned to pay claims from Isaias without the kind of financial strain that has forced some companies to raise rates sharply or pull back from the Florida market in past years. For policyholders, a well-capitalized insurer is less likely to delay claims or face solvency questions after a storm.
Have Florida's recent insurance market reforms been tested yet?
Palazola said recent reforms to Florida's insurance market have improved conditions for insurers operating in the state, but those reforms have not yet faced a major test. Hurricane Isaias, landing after the reforms took hold, is being watched as an early read on whether the changes hold up when real claims start coming in. Palazola's framing suggests the industry views this storm as a checkpoint rather than a worst-case scenario, since the losses he's projecting are on the lower end of what a major Florida hurricane could produce.
What should Florida homeowners and insurance investors watch next?
For homeowners in the storm's path, the practical question is how quickly claims get processed and whether insurers' improved capital position translates into faster payouts. For investors, Palazola's single-digit-billions estimate is the number to compare against actual reported losses as insurers release third-quarter and fourth-quarter results in the coming months. If losses come in near that estimate, it would support the idea that building codes and the reform package are working as intended. If losses run higher, it could reopen questions about whether Florida's insurance market is as stable as recent reforms suggested.
None of the figures in Palazola's interview are final. Insured loss estimates for major storms typically get revised as claims are filed and adjusters complete inspections, a process that can take weeks or months. Bloomberg has not published a specific dollar range beyond "single-digit billions," and no other insurer, state regulator, or catastrophe modeling firm has yet issued a competing figure for Hurricane Isaias.
Questions
How much could Hurricane Isaias cost insurers?
Bloomberg Intelligence analyst Matthew Palazola estimates insured losses in the single-digit billions of dollars.
Why are losses expected to stay relatively low?
Palazola points to stronger Florida building codes and insurer capital rebuilt over two mild hurricane seasons, even as property values rise.