business
Global Economy Muddles Through Despite Wars, IMF Meeting Shows
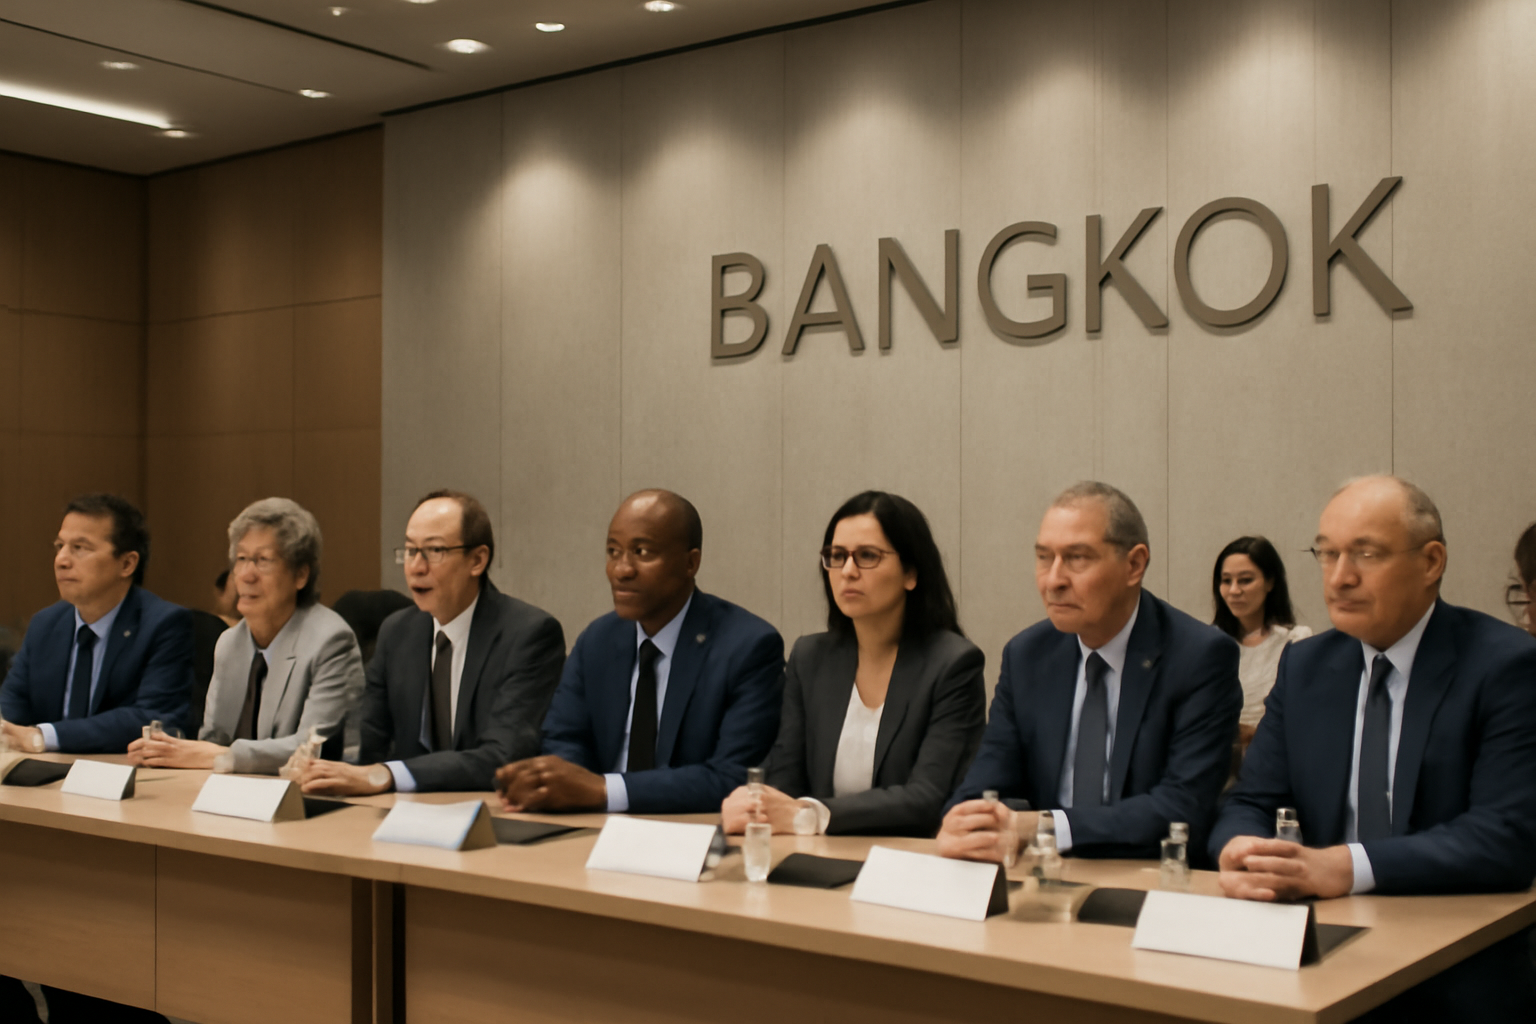
Finance ministers and central bank governors gathered this week in Bangkok for the International Monetary Fund's annual meetings are confronting a global economy battered by two regional wars, an energy shock and rising borrowing costs, yet one that has so far avoided a full-blown crisis, according to an analysis published by Guardian economics commentator Larry Elliott on Oct. 15.
Elliott writes that the resilience is notable given the scale of the headwinds. "Two big regional wars are destabilising prices and supply chains everywhere," he writes, adding that businesses and consumers are feeling a serious energy shock while inflation has made it more expensive for governments to finance debt. China and the United States remain at odds over trade, he notes. Even so, Elliott writes, the impact on growth has been "modest," and the meetings have not had to grapple with anything resembling the 2008 banking meltdown that coincided with a previous IMF gathering.
What is keeping the global economy from a full-blown crisis?
Elliott identifies three specific forces behind the better-than-expected performance. The first is heavy investment in artificial intelligence, which he says has been especially important in the United States — currently the fastest-growing economy among G7 members year on year, per his analysis. The second is that countries have drawn down existing oil inventories to offset lost crude supply from the Middle East, a step Elliott says has kept prices from climbing even more sharply. The third is China's reliance on exporting low-cost goods, which he writes is holding down import prices elsewhere in the world.
How unusual is this outcome historically?
Elliott frames the result as a break from precedent. Oil shocks of the size seen since the start of the Iran war have historically produced "a marked and immediate impact" on growth and inflation, he writes, but that pattern has not repeated this time. He credits the IMF for acknowledging the broader trend, writing that the institution "is right when it says countries have shown resilience when having to cope with so many headwinds."
"It could have been worse. A lot worse." — Larry Elliott, writing in the Guardian
What did the IMF say about the UK specifically?
Among the individual findings in Elliott's account, the IMF upgraded its growth forecast for the United Kingdom this year and praised the government's deficit-reduction plan, according to the analysis. The piece does not detail the size of the revised forecast or the specific deficit targets involved.
Why does multilateral cooperation remain unlikely?
Elliott's central argument is that the ministers and governors meeting in Bangkok understand the need for coordinated action across the fractures in the global economy — the wars, the energy shock, the China-US trade standoff — but he assesses that there is "little chance" of that cooperation materializing. The piece frames this as the core tension of the gathering: officials recognizing a shared problem while national interests and existing disputes make a unified response unlikely.
What comes next for the global economy?
The analysis warns that the current calm should not be mistaken for durability. Elliott's framing — that a storm is coming even as the economy muddles through — rests on the idea that the three stabilizing forces he identifies, AI-driven investment, drawn-down oil stockpiles, and China's export pricing, are not permanent fixes. Inventories can only be run down for so long, and the piece does not specify how long the AI investment boom or China's current export strategy can keep offsetting the other pressures.
What to watch
- Whether oil inventories, already drawn down to cushion the Middle East supply loss, can continue absorbing shocks without a renewed price spike.
- Whether AI-related investment in the United States keeps outpacing the rest of the G7 or begins to cool.
- Any shift in the US-China trade standoff coming out of discussions tied to the IMF meetings in Bangkok.
- Follow-through on the UK's deficit-reduction plan after the IMF's upgraded growth forecast.
- Signs of whether finance ministers move beyond acknowledging the need for cooperation toward actual coordinated policy steps.
The IMF meetings in Bangkok continue this week, with finance ministers and central bank governors from member countries addressing the mix of war-driven supply disruptions, energy costs and debt-financing pressures described in Elliott's analysis. Read the full piece at The Guardian.
Questions
Why hasn't the global economy fallen into crisis despite wars and an energy shock?
According to Larry Elliott's Guardian analysis, heavy AI investment in the U.S., drawn-down oil inventories offsetting lost Middle East crude, and China's low-cost export strategy have together muted the impact.
What did the IMF say about the UK economy at the Bangkok meetings?
The IMF upgraded its growth forecast for the UK this year and praised the government's deficit-reduction plan, per the Guardian's coverage of the annual meetings.